


 Home
VCs and founders crown AI startups with inflated ARR
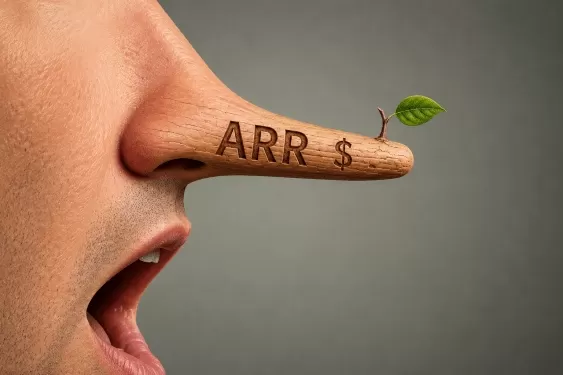
Last month, Scott Stevenson, co-founder and CEO of the legal AI startup Spellbook, posted on X to expose what he called a "massive scam" among AI startups: inflating the revenue figures they publicly announce.
He wrote: "The reason many AI startups are smashing revenue records is that they're using a dishonest metric. The world's largest funds are backing this and misleading journalists for PR coverage."
Stevenson is not the first to argue that annual recurring revenue (ARR) — a metric traditionally used to aggregate annual revenue from active customers under contract — is being distorted by some AI companies beyond recognition. Various aspects of ARR manipulation have been covered in numerous other news reports and social media posts.
However, Stevenson's tweet appeared to strike a particular nerve in the AI startup community, garnering over 200 reshares and comments from prominent investors, many founders, and even a few headlines.
"Scott at Spellbook did a great job of highlighting what you might call some bad behavior by certain companies," said Jack Newton, co-founder and CEO of legal startup Clio, to TechCrunch. He added that the post brought much-needed attention to the topic, referencing an explanatory post from YC's Garry Tan about proper revenue metrics.
TechCrunch interviewed more than a dozen founders, investors, and startup finance professionals to evaluate whether ARR inflation is as widespread as Stevenson suggests.
Indeed, our sources — many of whom spoke on condition of anonymity — confirmed that fudged ARR in public declarations is common among startups, and that in many cases, investors are aware of the exaggerations.
Not Quite Revenue Yet
The primary obfuscation tactic is substituting "contracted ARR," sometimes called "committed ARR" (CARR), and simply labeling it as ARR.
"For sure they are reporting CARR as ARR," one investor said. "When one startup does it in a category, it's hard not to do it yourself just to keep up."
ARR is a metric that has been established and trusted since the cloud era to indicate total sales of products where usage — and therefore payments — is metered over time. Accountants do not formally audit or sign off on ARR, mainly because generally accepted accounting principles (GAAP) focus on historical, already-collected revenue rather than future revenue.
ARR was intended to show the total value of signed-and-sealed sales, typically multi-year contracts. (Today, this concept is often referred to by another name: remaining performance obligations.) Meanwhile, the term "revenue" is typically reserved for money already collected.
CARR is meant to be another way to track growth. But it's a much fuzzier metric than ARR because it counts revenue from signed customers who haven't yet been onboarded.
One VC told TechCrunch that he has seen companies where CARR is 70% higher than ARR, even though a significant portion of that contracted revenue will never actually materialize.
CARR "builds on the ARR concept by adding committed but not yet live contract values to total ARR," Bessemer Venture Partners (BVP) wrote in a 2021 blog post. Critically, though, BVP says, the startup is supposed to adjust CARR to account for expected customer churn (how many customers leave) and "downsell" (those who decide to buy less).
The main problem with CARR is counting revenue before a startup's product is implemented. If implementation is lengthy or goes wrong, clients may cancel during the trial before all — or any — of the contracted revenue has been collected.
Several investors told TechCrunch that they personally know of at least one high-profile enterprise startup that reported surpassing $100 million in ARR, when only a fraction of that revenue came from currently paying customers. The rest was from contracts that hadn't been deployed yet and in some cases may take a long time to implement the technology.
One former employee at a startup that routinely reported CARR as ARR told TechCrunch that the company counted at least one substantial, year-long free pilot as ARR. The company's board, including a VC from a large fund, was aware that the revenue from the eventual paying part of the contract had been counted in ARR during the lengthy pilot program, the person said. The board was also aware that the customer could cancel before paying the full contract amount.
The obvious problem with using CARR and calling it ARR is that it is far more susceptible to being "gamed" than traditional ARR. If a startup doesn't realistically account for churn and downsell, CARR can be inflated. For instance, a startup could offer big discounts for the first two years of a three-year contract and count the entire three years as CARR (or ARR), even though customers may not stick around to pay the higher prices in year three.
"I think Scott [Stevenson] is right. I've heard all sorts of anecdotes as well," Ross McNairn, co-founder and CEO of legal AI startup Wordsmith, told TechCrunch about ARR misrepresentations. "I speak to VCs all the time. They're like, 'There are some choppy, choppy standards out there.'"
Most cases are slightly less extreme. For instance, an employee at another startup described a discrepancy where marketing materials claimed $50 million in ARR, while the actual figure was $42 million.
However, this person claimed that investors had access to the company's books, which accurately reflected the lower amount. The source said some startups and their investors are comfortable playing fast and loose with their public metrics, partly because AI startups are growing so quickly that an $8 million gap is viewed as a rounding error they'll quickly grow into.
The Other, More Problematic "ARR"
There's another issue surrounding all those public ARR declarations. Sometimes founders use another measurement with the same "ARR" acronym and a similar name: annualized run-rate revenue.
This ARR is also controversial because it extrapolates current revenue over the next 12 months based on a given period's haul (e.g., a quarter, month, week, or even a day).
Since many AI companies charge based on usage or outcomes, that method of calculating annualized run-rate ARR can be misleading because revenue is no longer locked into predictable contracts.
Most people interviewed for this story said that ARR overstatements of all kinds are hardly a novel phenomenon, but startups have become far more aggressive amid the AI hype.
"The valuations have gotten higher, and so the incentives are stronger to do it," Michael Marks, a founding managing partner at Celesta Capital, told TechCrunch.
In the age of AI, startups are expected to grow much faster than ever before.
"Going from 1 to 3 to 9 to 27 is not interesting," Hemant Taneja, CEO and managing director of General Catalyst, said on the 20VC podcast last September, referring to the millions in ARR a startup is traditionally projected to hit each year. "You've got to go like 1 to 20 to 100."
The pressure to show rapid growth is prompting some VCs to support, or at least overlook, startups presenting inflated ARR figures to the public.
"There are definitely VCs in on this because they're incentivized to create a narrative that they have runaway winners. They're incentivized to get press coverage for their companies," Stevenson told TechCrunch.
Newton, whose legal AI startup Clio was valued at $5 billion last fall, also alleges that VCs are often aware but silent about ARR misrepresentations. "We see some investors looking the other way when their own companies are inflating numbers because it makes them look good from the outside in," he told TechCrunch.
What VCs Really Think
Other investors who spoke with TechCrunch say there is no reason for VCs to expose the overstatements.
By turning a blind eye to public pronouncements of inflated ARR, VCs are effectively helping to kingmake their own portfolio companies. When a startup publicly reports high revenue, it is more likely to attract the best talent and customers who believe the company is the undisputed winner in its category.
"Investors can't call it out," a VC told TechCrunch. "Everyone has a company monetizing CARR as ARR."
Still, anyone intimately familiar with the industry's intricacies has a hard time believing that some of these startups actually reached $100 million in ARR within a few years of launch.
"To everyone who's inside, it just feels fake," said Alex Cohen, co-founder and CEO of health AI startup Hello Patient. "You read the headlines and you're like, 'I don't believe it.'"
However, not all startups feel comfortable representing growth by reporting CARR instead of ARR. They prefer to be clean and clear about their numbers, in part because they understand that public markets measure software companies on ARR rather than CARR. These founders prioritize transparency.
Wordsmith's McNairn, who remembers the struggle startups faced justifying high valuations after the 2022 market correction, said he doesn't want to create an even higher hurdle by exaggerating his startup's revenue.
"I think it is short-sighted, and I think that when you do things like that for a short-term gain, you're overinflating already crazy high multiples," he said. "I think it's super bad hygiene, and it's going to come back and bite you."
Related article
 Crypto exchange OKX aims to empower AI agents to hire and pay each other
As AI agents start serving individuals and collaborating with each other, they require mechanisms to locate tasks, compensate for services, and establish credibility. Crypto exchange OKX anticipates this future is arriving sooner than anticipated, in
Thiel-backed startup claims AI can judge journalism, despite risks to whistleblowers
Following his role in the lawsuit that led to Gawker’s bankruptcy, Aron D’Souza identified a critical flaw in the American media landscape: individuals harmed by coverage lacked effective means to respond.His answer is technology. D’Souza’s new ventu
Prentis, New AI Lab Co-Founded by Reid Hoffman and Marc Pincus, in Talks to Raise $100M
Prentis, an emerging AI research lab specializing in computer-use models, is co-founded by serial entrepreneur Ritankar Das alongside tech industry leaders Reid Hoffman and Marc Pincus. According to two individuals familiar with the matter, the compa
Related Special Topic Recommendations
writing
 AI Article Outline Tools for Long Form Writing
2026 Latest Best Top-Rated AI Article Outline Tools for Long Form Writing! This curated collection features powerful, game-changing tools that deliver accurate, structured outlines with real-world tests to boost writing efficiency significantly. XIX.AI is part of this elite selection. Get a free vs paid comparison to help you choose the perfect tool. Explore now and Unlock your AI edge!
 9 tools
 xix.ai
chatbot
Best AI Roleplay Chat Apps for Language Practice, Interview Prep, and Daily Fluency
2026 Latest Best Top-rated AI Roleplay Chat Apps for Language Practice, Interview Prep, and Daily Fluency! XIX.AI curates a powerful game-changing collection that offers free vs paid comparison, real-world tests, and updated rankings weekly. These must-try tools help you boost writing skills, overcome fluency challenges, and improve communication efficiency across all daily scenarios. Explore now to discover your perfect tool for language growth!
10 tools
xix.ai
Music composition
AI Stem Separation Tools for Remix Production, Sampling Prep, and Karaoke Masters
2026 Latest Best Top-rated AI Stem Separation Tools Curated for Remix Production, Sampling Prep, and Karaoke Masters. These powerful game-changing tools offer real-world tests to deliver precise audio isolation, boosting productivity significantly. XIX.AI provides a weekly updated free vs paid comparison guide to help you find the must-try solution that suits your needs. Explore now to unlock your AI edge.
8 tools
xix.ai
Data Analysis
AI SQL Copilots for Revenue Dashboards, Funnel Analysis, and Product Metrics
2026 Latest Best AI SQL Copilots Ranked Top-Rated! XIX.AI curates a powerful game-changing collection for weekly updated real-world tests. These must-try tools help you generate accurate revenue dashboards, analyze sales funnels, and track product metrics swiftly, boosting productivity massively. Explore now to Discover your perfect tool for data-driven decision making! 238 characters
9 tools
xix.ai
Music composition
Best AI Melody Writing Tools for Song Drafts
2026 Latest Best Top-Rated AI Melody Writing Tools for Song Drafts! XIX.AI has curated a highly powerful game-changing collection that goes through rigorous real-world tests to deliver the best writing experience. You can find detailed free vs paid comparisons, accurate rankings, and must-try options designed to help you create stunning song drafts effortlessly and boost your creative productivity significantly. Explore now to discover your perfect tool!
8 tools
xix.ai
chatbot
Best AI Conversation Trainer Tools for Interview Practice
2026 Latest Best Top-rated AI Conversation Trainer Tools for Interview Practice are here on XIX.AI! This curated collection features powerful, game-changing tools that go through rigorous real-world tests to deliver accurate feedback. You’ll find a free vs paid comparison and detailed rankings to help you choose the must-try option that boosts your confidence and skills. Explore now to Discover your perfect tool for interview success!
12 tools
xix.ai

 Comments (10)
0/500
![RogerGonzalez]()
¿Es mentira el ARR? Las startups de IA inflan números y los VC siguen comprando.
![MatthewGonzalez]()
ARR inflado é a nova norma? VCs e fundadores jogam esse jogo de mentirinhas.
![FrankRoberts]()
Die ARR-Blase bei KI-Startups ist riesig. VC's kaufen einfach alles, was glänzt.
![GaryWilson]()
AI 스타트업의 ARR inflation이 심하네. VC들도 그냥 돈 던지는 것 같아.
![HenryWalker]()
Инфляция ARR у AI-стартапов зашкаливает. VC просто кидают деньги, не глядя.
![PaulYoung]()
Des ARR gonflés, des VCs aveugles. L'IA est-elle devenue une arnaque légale ? 🤔
Last month, Scott Stevenson, co-founder and CEO of the legal AI startup Spellbook, posted on X to expose what he called a "massive scam" among AI startups: inflating the revenue figures they publicly announce.
He wrote: "The reason many AI startups are smashing revenue records is that they're using a dishonest metric. The world's largest funds are backing this and misleading journalists for PR coverage."
Stevenson is not the first to argue that annual recurring revenue (ARR) — a metric traditionally used to aggregate annual revenue from active customers under contract — is being distorted by some AI companies beyond recognition. Various aspects of ARR manipulation have been covered in numerous other news reports and social media posts.
However, Stevenson's tweet appeared to strike a particular nerve in the AI startup community, garnering over 200 reshares and comments from prominent investors, many founders, and even a few headlines.
"Scott at Spellbook did a great job of highlighting what you might call some bad behavior by certain companies," said Jack Newton, co-founder and CEO of legal startup Clio, to TechCrunch. He added that the post brought much-needed attention to the topic, referencing an explanatory post from YC's Garry Tan about proper revenue metrics.
TechCrunch interviewed more than a dozen founders, investors, and startup finance professionals to evaluate whether ARR inflation is as widespread as Stevenson suggests.
Indeed, our sources — many of whom spoke on condition of anonymity — confirmed that fudged ARR in public declarations is common among startups, and that in many cases, investors are aware of the exaggerations.
Not Quite Revenue Yet
The primary obfuscation tactic is substituting "contracted ARR," sometimes called "committed ARR" (CARR), and simply labeling it as ARR.
"For sure they are reporting CARR as ARR," one investor said. "When one startup does it in a category, it's hard not to do it yourself just to keep up."
ARR is a metric that has been established and trusted since the cloud era to indicate total sales of products where usage — and therefore payments — is metered over time. Accountants do not formally audit or sign off on ARR, mainly because generally accepted accounting principles (GAAP) focus on historical, already-collected revenue rather than future revenue.
ARR was intended to show the total value of signed-and-sealed sales, typically multi-year contracts. (Today, this concept is often referred to by another name: remaining performance obligations.) Meanwhile, the term "revenue" is typically reserved for money already collected.
CARR is meant to be another way to track growth. But it's a much fuzzier metric than ARR because it counts revenue from signed customers who haven't yet been onboarded.
One VC told TechCrunch that he has seen companies where CARR is 70% higher than ARR, even though a significant portion of that contracted revenue will never actually materialize.
CARR "builds on the ARR concept by adding committed but not yet live contract values to total ARR," Bessemer Venture Partners (BVP) wrote in a 2021 blog post. Critically, though, BVP says, the startup is supposed to adjust CARR to account for expected customer churn (how many customers leave) and "downsell" (those who decide to buy less).
The main problem with CARR is counting revenue before a startup's product is implemented. If implementation is lengthy or goes wrong, clients may cancel during the trial before all — or any — of the contracted revenue has been collected.
Several investors told TechCrunch that they personally know of at least one high-profile enterprise startup that reported surpassing $100 million in ARR, when only a fraction of that revenue came from currently paying customers. The rest was from contracts that hadn't been deployed yet and in some cases may take a long time to implement the technology.
One former employee at a startup that routinely reported CARR as ARR told TechCrunch that the company counted at least one substantial, year-long free pilot as ARR. The company's board, including a VC from a large fund, was aware that the revenue from the eventual paying part of the contract had been counted in ARR during the lengthy pilot program, the person said. The board was also aware that the customer could cancel before paying the full contract amount.
The obvious problem with using CARR and calling it ARR is that it is far more susceptible to being "gamed" than traditional ARR. If a startup doesn't realistically account for churn and downsell, CARR can be inflated. For instance, a startup could offer big discounts for the first two years of a three-year contract and count the entire three years as CARR (or ARR), even though customers may not stick around to pay the higher prices in year three.
"I think Scott [Stevenson] is right. I've heard all sorts of anecdotes as well," Ross McNairn, co-founder and CEO of legal AI startup Wordsmith, told TechCrunch about ARR misrepresentations. "I speak to VCs all the time. They're like, 'There are some choppy, choppy standards out there.'"
Most cases are slightly less extreme. For instance, an employee at another startup described a discrepancy where marketing materials claimed $50 million in ARR, while the actual figure was $42 million.
However, this person claimed that investors had access to the company's books, which accurately reflected the lower amount. The source said some startups and their investors are comfortable playing fast and loose with their public metrics, partly because AI startups are growing so quickly that an $8 million gap is viewed as a rounding error they'll quickly grow into.
The Other, More Problematic "ARR"
There's another issue surrounding all those public ARR declarations. Sometimes founders use another measurement with the same "ARR" acronym and a similar name: annualized run-rate revenue.
This ARR is also controversial because it extrapolates current revenue over the next 12 months based on a given period's haul (e.g., a quarter, month, week, or even a day).
Since many AI companies charge based on usage or outcomes, that method of calculating annualized run-rate ARR can be misleading because revenue is no longer locked into predictable contracts.
Most people interviewed for this story said that ARR overstatements of all kinds are hardly a novel phenomenon, but startups have become far more aggressive amid the AI hype.
"The valuations have gotten higher, and so the incentives are stronger to do it," Michael Marks, a founding managing partner at Celesta Capital, told TechCrunch.
In the age of AI, startups are expected to grow much faster than ever before.
"Going from 1 to 3 to 9 to 27 is not interesting," Hemant Taneja, CEO and managing director of General Catalyst, said on the 20VC podcast last September, referring to the millions in ARR a startup is traditionally projected to hit each year. "You've got to go like 1 to 20 to 100."
The pressure to show rapid growth is prompting some VCs to support, or at least overlook, startups presenting inflated ARR figures to the public.
"There are definitely VCs in on this because they're incentivized to create a narrative that they have runaway winners. They're incentivized to get press coverage for their companies," Stevenson told TechCrunch.
Newton, whose legal AI startup Clio was valued at $5 billion last fall, also alleges that VCs are often aware but silent about ARR misrepresentations. "We see some investors looking the other way when their own companies are inflating numbers because it makes them look good from the outside in," he told TechCrunch.
What VCs Really Think
Other investors who spoke with TechCrunch say there is no reason for VCs to expose the overstatements.
By turning a blind eye to public pronouncements of inflated ARR, VCs are effectively helping to kingmake their own portfolio companies. When a startup publicly reports high revenue, it is more likely to attract the best talent and customers who believe the company is the undisputed winner in its category.
"Investors can't call it out," a VC told TechCrunch. "Everyone has a company monetizing CARR as ARR."
Still, anyone intimately familiar with the industry's intricacies has a hard time believing that some of these startups actually reached $100 million in ARR within a few years of launch.
"To everyone who's inside, it just feels fake," said Alex Cohen, co-founder and CEO of health AI startup Hello Patient. "You read the headlines and you're like, 'I don't believe it.'"
However, not all startups feel comfortable representing growth by reporting CARR instead of ARR. They prefer to be clean and clear about their numbers, in part because they understand that public markets measure software companies on ARR rather than CARR. These founders prioritize transparency.
Wordsmith's McNairn, who remembers the struggle startups faced justifying high valuations after the 2022 market correction, said he doesn't want to create an even higher hurdle by exaggerating his startup's revenue.
"I think it is short-sighted, and I think that when you do things like that for a short-term gain, you're overinflating already crazy high multiples," he said. "I think it's super bad hygiene, and it's going to come back and bite you."








 Crypto exchange OKX aims to empower AI agents to hire and pay each other
As AI agents start serving individuals and collaborating with each other, they require mechanisms to locate tasks, compensate for services, and establish credibility. Crypto exchange OKX anticipates this future is arriving sooner than anticipated, in
 Thiel-backed startup claims AI can judge journalism, despite risks to whistleblowers
Following his role in the lawsuit that led to Gawker’s bankruptcy, Aron D’Souza identified a critical flaw in the American media landscape: individuals harmed by coverage lacked effective means to respond.His answer is technology. D’Souza’s new ventu
 Prentis, New AI Lab Co-Founded by Reid Hoffman and Marc Pincus, in Talks to Raise $100M
Prentis, an emerging AI research lab specializing in computer-use models, is co-founded by serial entrepreneur Ritankar Das alongside tech industry leaders Reid Hoffman and Marc Pincus. According to two individuals familiar with the matter, the compa

2026 Latest Best Top-Rated AI Article Outline Tools for Long Form Writing! This curated collection features powerful, game-changing tools that deliver accurate, structured outlines with real-world tests to boost writing efficiency significantly. XIX.AI is part of this elite selection. Get a free vs paid comparison to help you choose the perfect tool. Explore now and Unlock your AI edge!
9 tools
xix.ai

2026 Latest Best Top-rated AI Roleplay Chat Apps for Language Practice, Interview Prep, and Daily Fluency! XIX.AI curates a powerful game-changing collection that offers free vs paid comparison, real-world tests, and updated rankings weekly. These must-try tools help you boost writing skills, overcome fluency challenges, and improve communication efficiency across all daily scenarios. Explore now to discover your perfect tool for language growth!
10 tools
xix.ai

2026 Latest Best Top-rated AI Stem Separation Tools Curated for Remix Production, Sampling Prep, and Karaoke Masters. These powerful game-changing tools offer real-world tests to deliver precise audio isolation, boosting productivity significantly. XIX.AI provides a weekly updated free vs paid comparison guide to help you find the must-try solution that suits your needs. Explore now to unlock your AI edge.
8 tools
xix.ai

2026 Latest Best AI SQL Copilots Ranked Top-Rated! XIX.AI curates a powerful game-changing collection for weekly updated real-world tests. These must-try tools help you generate accurate revenue dashboards, analyze sales funnels, and track product metrics swiftly, boosting productivity massively. Explore now to Discover your perfect tool for data-driven decision making! 238 characters
9 tools
xix.ai

2026 Latest Best Top-Rated AI Melody Writing Tools for Song Drafts! XIX.AI has curated a highly powerful game-changing collection that goes through rigorous real-world tests to deliver the best writing experience. You can find detailed free vs paid comparisons, accurate rankings, and must-try options designed to help you create stunning song drafts effortlessly and boost your creative productivity significantly. Explore now to discover your perfect tool!
8 tools
xix.ai

2026 Latest Best Top-rated AI Conversation Trainer Tools for Interview Practice are here on XIX.AI! This curated collection features powerful, game-changing tools that go through rigorous real-world tests to deliver accurate feedback. You’ll find a free vs paid comparison and detailed rankings to help you choose the must-try option that boosts your confidence and skills. Explore now to Discover your perfect tool for interview success!
12 tools
xix.ai

¿Es mentira el ARR? Las startups de IA inflan números y los VC siguen comprando.
ARR inflado é a nova norma? VCs e fundadores jogam esse jogo de mentirinhas.
Die ARR-Blase bei KI-Startups ist riesig. VC's kaufen einfach alles, was glänzt.
AI 스타트업의 ARR inflation이 심하네. VC들도 그냥 돈 던지는 것 같아.
Инфляция ARR у AI-стартапов зашкаливает. VC просто кидают деньги, не глядя.
Des ARR gonflés, des VCs aveugles. L'IA est-elle devenue une arnaque légale ? 🤔












