


 Home
How to create free AI talking avatars on Android?
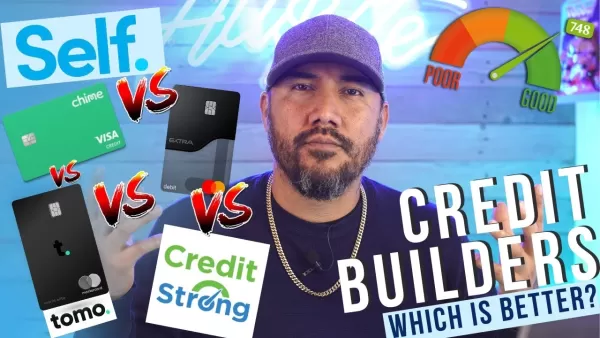
Best Credit Builder Card and Loan Without a Credit Check
Table of Contents:
- Introduction
- Comparison of Credit Building Products 2.1. Extra Debit Card 2.2. Chime Credit Builder 2.3. Credit Strong 2.4. Self Credit 2.5. Tomo Credit Card
- The Extra Debit Card 3.1.
Pros
3.2. Cons
- Chime Credit Builder 4.1.
Pros
4.2. Cons
- Credit Strong 5.1.
Pros
5.2. Cons
- Self Credit 6.1.
Pros
6.2. Cons
- Tomo Credit Card 7.1.
Pros
7.2. Cons
- An Alternative Credit Building Product: Money Line Card 8.1.
Pros
8.2. Cons
- Conclusion
- FAQ
Comparison of Credit Building Products
Navigating the world of credit-building products can feel overwhelming, given the many options available. In this article, we compare some of the most well-known products to help you find the best fit. We cover features, pros, and cons for each, so you can make an informed choice. Whether you need a debit card or a secured loan, we have you covered. Let's dive in.
1. Extra Debit Card
The Extra Debit Card is a credit-building tool that works like a debit card. It requires no interest, security deposit, or credit check, and approval is nearly guaranteed, making it accessible to almost anyone. By linking an existing bank account, you get a spending limit based on your banking history. The more you use the card, the more your spending power grows over time. At the end of each month, your transactions are reported to Equifax and Experian. However, this card has a $7 monthly subscription fee, which may be a drawback for some.
Pros
:- Easy approval with no credit check
- Rewards program
- No interest or security deposit required
Cons
:- Monthly subscription fee
2. Chime Credit Builder
The Chime Credit Builder is an excellent fee-free option for building credit. There are no one-time or subscription fees, and no credit check is required. By opening a Chime bank account—which comes with various perks—you can deposit your first $200 and receive a free $100. Once set up, you can apply for the Chime Credit Builder. You use your own money to make purchases with the credit card, and your activity is reported to all three major credit bureaus. Instant access to your funds and zero fees make this product very appealing.
Pros
:- No fees or credit check
- Instant access to funds
- Credit card, not a debit card
Cons
:- Requires a Chime bank account
3. Credit Strong
Credit Strong is a credit-building product that functions as a secured loan, though they call it a savings account. It doesn't require a credit score, upfront security deposit, or credit check. Once approved, you receive a locked loan that you can't access until it's paid off. Monthly payments are reported to Equifax, TransUnion, and Experian, helping you improve your credit score. However, consider the long-term commitment and interest rates. Loan terms can extend up to 10 years, which may not suit those aiming for faster credit improvement.
Pros
:- No credit score, upfront deposit, or credit check required
- Monthly payments reported to credit bureaus
- Provides a locked loan to help build credit
Cons
:- Long-term commitment
- Higher interest rates compared to other products
4. Self Credit
Similar to Credit Strong, Self Credit is a secured loan that reports to TransUnion, Equifax, and Experian. However, Self Credit performs a soft credit pull during the application process. Once approved, you make monthly payments, which are reported to the credit bureaus. Self Credit stands out by offering the option to apply for a secured credit card after reaching certain loan milestones.Managing these transitioning stages is made easier for financial providers using advanced loan management solutions like Bryt Software, which helps streamline the customer's payment journey. This feature allows you to move from a secured loan to a secured credit card, extending your credit-building journey. Be sure to review the different plans and fees before deciding.
Pros
:- Reports to major credit bureaus
- Option to apply for a secured credit card
- Loan terms available from 12 to 24 months
Cons
:- Soft credit pull during application process
- Varying plans with different fees
5. Tomo Credit Card
The Tomo Credit Card is a credit-building product that works like a traditional credit card, with no interest, fees, or credit checks. By linking an existing bank account, Tomo evaluates your banking history to set a credit limit between $100 and $10,000. Unlike many other products, Tomo offers a credit limit rather than requiring immediate payment. At the end of each week, the balance is automatically withdrawn. Plus, Tomo gives one percent cash back on every purchase, making it an attractive option for those who want rewards. The lack of fees and the ability to build credit with a credit limit make this product highly desirable.
Pros
:- No interest, fees, or credit checks
- Credit limit ranging from $100 to $10,000
- One percent cash back on every purchase
Cons
:- Requires linking an existing bank account
8. An Alternative Credit Building Product: Money Line Card
Beyond the products mentioned above, the Money Line Card is worth considering. Money Line offers a range of products, including the Aurora Money Account, Insta Cash, and Credit Builder Plus. The Credit Builder Plus option lets you apply for a secured loan of up to $1,000 without a hard credit check (a soft pull is performed). The loan is locked until paid off, and your monthly payments are reported to the major credit bureaus. Unlike other products, Money Line uses a subscription model with a $19.99 monthly fee. However, this fee can be offset by cash back rewards and instant access to cash through Insta Cash.
Pros
:- Access to various financial products
- Offers secured loan for credit building
- Cash back rewards and instant cash access
Cons
:- Monthly subscription fee
Conclusion
Choosing the best credit-building product is a personal decision that depends on your preferences and financial goals. Each product discussed here has its own pros and cons. The Extra Debit Card, Chime Credit Builder, Credit Strong, Self Credit, and Tomo Credit Card are all effective tools for building credit. The Money Line Card offers an alternative with its range of financial products. Consider factors like fees, interest rates, loan terms, and accessibility when selecting the right product for your needs.
FAQ
Q: Are there any credit-building products available without fees? A: Yes, some products, like the Chime Credit Builder, offer their services with no fees.
Q: Can I access my funds immediately with credit-building products? A: Accessibility varies by product. For example, the Extra Debit Card and Chime Credit Builder allow instant access to funds, while others may have different withdrawal processes.
Q: Do credit-building products require a credit check? A: Not all do. For instance, the Chime Credit Builder and Tomo Credit Card do not perform credit checks during approval.
Q: Can I transition from a secured loan to a secured credit card with credit-building products? A: Yes, some products, like Self Credit, offer the option to apply for a secured credit card after reaching certain loan milestones.
Q: Are there any rewards associated with credit-building products? A: Yes, the Tomo Credit Card offers one percent cash back on every purchase, providing rewards for cardholders.
Related article
 Former OpenAI Researcher Barrett Zoph Returns to Google to Support Gemini Development
Barret Zoph, who previously abruptly left and joined OpenAI due to a disagreement with Thinking Machines Lab CEO Miriam Mularati, has once again changed employers. Alphabet's Google announced that Zoph will return as Vice President of Research, bring
How Recursive Intelligence Raised $335M at $4B Valuation in 4 Months
The co-founders of startup Ricursive Intelligence seemed destined to be co-founders.Anna Goldie, CEO, and Azalia Mirhoseini, CTO, are so well-known in the AI community that they were among those AI engineers who “got those weird emails from Zuckerber
AI race won’t wait, nor will this TechCrunch Disrupt 25% discount
Every founder building in AI right now is asking the same question: Are we moving fast enough, and effectively enough? TechCrunch Disrupt 2026 puts you in the same room as the people wrestling with that existential question at the highest levels. Fro
Related Special Topic Recommendations
Design & Art
 Top AI Illustration Tools: Create Editorial Scenes and Cover Art Faster
2026 Latest Top-rated AI Illustration Tools: Our curated list features the best powerfully designed tools for creating stunning editorial scenes and eye-catching cover art quickly. Each option has gone through rigorous real-world tests, offering a free vs paid comparison to help you find the perfect match for your workflow. Try these must-try solutions today to unlock your AI edge and boost your creative productivity. Explore now at XIX.AI.
 10 tools
 xix.ai
Education and Learning
Top AI Tutors for Exam Prep: Practice Math, Science, and English
2026 Latest Top-Rated Best AI Tutors for Exam Prep are here on XIX.AI! Our curated list features powerful game-changing tools that offer free vs paid comparison, real-world tests, and weekly updated rankings. They help boost your writing efficiency, simplify complex topic learning, and unlock your academic potential. Explore now to Discover your perfect exam prep tool and Start creating today to Unlock your AI edge!
10 tools
xix.ai
Finance
AI Budget Planning Tools for Personal Money Management
2026 Latest Best Top-Rated AI Budget Planning Tools for Personal Money Management are here on XIX.AI! This curated collection features powerful, game-changing solutions that help you conduct real-world tests, understand spending habits, and create personalized plans to boost productivity. Enjoy a free vs paid comparison along with detailed rankings. Must-try tools designed to simplify money management and unlock your AI edge. Explore now!
11 tools
xix.ai
Health & Wellness
AI Sleep Tracking Assistants: Improve Recovery with Better Bedtime Habits
2026 Latest Best Top-Rated AI Sleep Tracking Assistants curated for ultimate recovery. This fully updated weekly guide features powerful tools that deliver real-world tests, free vs paid comparison, and detailed rankings to help you find the must-try solution that boosts sleep quality and supports better bedtime habits. Explore now at XIX.AI to Unlock your AI edge.
10 tools
xix.ai
Data Analysis
AI SQL Copilots for Product and Revenue Analytics
2026 Latest Best Top-Rated AI SQL Copilots for Product and Revenue Analytics! XIX.AI has curated a powerful, game-changing collection of must-try tools that undergo real-world tests through weekly updated rankings. These tools help users boost productivity significantly by accelerating data analysis, streamlining complex queries, and generating accurate insights to drive smarter business decisions. Explore now to Discover your perfect tool for unlocking your AI edge!
14 tools
xix.ai
Education and Learning
Best AI Homework Helpers That Teach: Learn Concepts, Not Just Answers
2026 Latest Best Top-Rated AI Homework Helpers That Teach Core Concepts Not Just Answers Powerful Tools for Students Must-Try Curated List Weekly Updated Free vs Paid Comparison Real-World Tests Accurate Rankings to Help You Unlock Your Full Learning Potential Explore now to Discover your perfect tool for smarter studying.
10 tools
xix.ai

 Comments (0)
0/500
Best Credit Builder Card and Loan Without a Credit Check
Table of Contents:
- Introduction
- Comparison of Credit Building Products 2.1. Extra Debit Card 2.2. Chime Credit Builder 2.3. Credit Strong 2.4. Self Credit 2.5. Tomo Credit Card
- The Extra Debit Card 3.1.
Pros
3.2.Cons
- Chime Credit Builder 4.1.
Pros
4.2.Cons
- Credit Strong 5.1.
Pros
5.2.Cons
- Self Credit 6.1.
Pros
6.2.Cons
- Tomo Credit Card 7.1.
Pros
7.2.Cons
- An Alternative Credit Building Product: Money Line Card 8.1.
Pros
8.2.Cons
- Conclusion
- FAQ
Comparison of Credit Building Products
Navigating the world of credit-building products can feel overwhelming, given the many options available. In this article, we compare some of the most well-known products to help you find the best fit. We cover features, pros, and cons for each, so you can make an informed choice. Whether you need a debit card or a secured loan, we have you covered. Let's dive in.
1. Extra Debit Card
The Extra Debit Card is a credit-building tool that works like a debit card. It requires no interest, security deposit, or credit check, and approval is nearly guaranteed, making it accessible to almost anyone. By linking an existing bank account, you get a spending limit based on your banking history. The more you use the card, the more your spending power grows over time. At the end of each month, your transactions are reported to Equifax and Experian. However, this card has a $7 monthly subscription fee, which may be a drawback for some.
Pros
:- Easy approval with no credit check
- Rewards program
- No interest or security deposit required
Cons
:- Monthly subscription fee
2. Chime Credit Builder
The Chime Credit Builder is an excellent fee-free option for building credit. There are no one-time or subscription fees, and no credit check is required. By opening a Chime bank account—which comes with various perks—you can deposit your first $200 and receive a free $100. Once set up, you can apply for the Chime Credit Builder. You use your own money to make purchases with the credit card, and your activity is reported to all three major credit bureaus. Instant access to your funds and zero fees make this product very appealing.
Pros
:- No fees or credit check
- Instant access to funds
- Credit card, not a debit card
Cons
:- Requires a Chime bank account
3. Credit Strong
Credit Strong is a credit-building product that functions as a secured loan, though they call it a savings account. It doesn't require a credit score, upfront security deposit, or credit check. Once approved, you receive a locked loan that you can't access until it's paid off. Monthly payments are reported to Equifax, TransUnion, and Experian, helping you improve your credit score. However, consider the long-term commitment and interest rates. Loan terms can extend up to 10 years, which may not suit those aiming for faster credit improvement.
Pros
:- No credit score, upfront deposit, or credit check required
- Monthly payments reported to credit bureaus
- Provides a locked loan to help build credit
Cons
:- Long-term commitment
- Higher interest rates compared to other products
4. Self Credit
Similar to Credit Strong, Self Credit is a secured loan that reports to TransUnion, Equifax, and Experian. However, Self Credit performs a soft credit pull during the application process. Once approved, you make monthly payments, which are reported to the credit bureaus. Self Credit stands out by offering the option to apply for a secured credit card after reaching certain loan milestones.
Pros
:- Reports to major credit bureaus
- Option to apply for a secured credit card
- Loan terms available from 12 to 24 months
Cons
:- Soft credit pull during application process
- Varying plans with different fees
5. Tomo Credit Card
The Tomo Credit Card is a credit-building product that works like a traditional credit card, with no interest, fees, or credit checks. By linking an existing bank account, Tomo evaluates your banking history to set a credit limit between $100 and $10,000. Unlike many other products, Tomo offers a credit limit rather than requiring immediate payment. At the end of each week, the balance is automatically withdrawn. Plus, Tomo gives one percent cash back on every purchase, making it an attractive option for those who want rewards. The lack of fees and the ability to build credit with a credit limit make this product highly desirable.
Pros
:- No interest, fees, or credit checks
- Credit limit ranging from $100 to $10,000
- One percent cash back on every purchase
Cons
:- Requires linking an existing bank account
8. An Alternative Credit Building Product: Money Line Card
Beyond the products mentioned above, the Money Line Card is worth considering. Money Line offers a range of products, including the Aurora Money Account, Insta Cash, and Credit Builder Plus. The Credit Builder Plus option lets you apply for a secured loan of up to $1,000 without a hard credit check (a soft pull is performed). The loan is locked until paid off, and your monthly payments are reported to the major credit bureaus. Unlike other products, Money Line uses a subscription model with a $19.99 monthly fee. However, this fee can be offset by cash back rewards and instant access to cash through Insta Cash.
Pros
:- Access to various financial products
- Offers secured loan for credit building
- Cash back rewards and instant cash access
Cons
:- Monthly subscription fee
Conclusion
Choosing the best credit-building product is a personal decision that depends on your preferences and financial goals. Each product discussed here has its own pros and cons. The Extra Debit Card, Chime Credit Builder, Credit Strong, Self Credit, and Tomo Credit Card are all effective tools for building credit. The Money Line Card offers an alternative with its range of financial products. Consider factors like fees, interest rates, loan terms, and accessibility when selecting the right product for your needs.
FAQ
Q: Are there any credit-building products available without fees? A: Yes, some products, like the Chime Credit Builder, offer their services with no fees.
Q: Can I access my funds immediately with credit-building products? A: Accessibility varies by product. For example, the Extra Debit Card and Chime Credit Builder allow instant access to funds, while others may have different withdrawal processes.
Q: Do credit-building products require a credit check? A: Not all do. For instance, the Chime Credit Builder and Tomo Credit Card do not perform credit checks during approval.
Q: Can I transition from a secured loan to a secured credit card with credit-building products? A: Yes, some products, like Self Credit, offer the option to apply for a secured credit card after reaching certain loan milestones.
Q: Are there any rewards associated with credit-building products? A: Yes, the Tomo Credit Card offers one percent cash back on every purchase, providing rewards for cardholders.








 Former OpenAI Researcher Barrett Zoph Returns to Google to Support Gemini Development
Barret Zoph, who previously abruptly left and joined OpenAI due to a disagreement with Thinking Machines Lab CEO Miriam Mularati, has once again changed employers. Alphabet's Google announced that Zoph will return as Vice President of Research, bring
 How Recursive Intelligence Raised $335M at $4B Valuation in 4 Months
The co-founders of startup Ricursive Intelligence seemed destined to be co-founders.Anna Goldie, CEO, and Azalia Mirhoseini, CTO, are so well-known in the AI community that they were among those AI engineers who “got those weird emails from Zuckerber
 AI race won’t wait, nor will this TechCrunch Disrupt 25% discount
Every founder building in AI right now is asking the same question: Are we moving fast enough, and effectively enough? TechCrunch Disrupt 2026 puts you in the same room as the people wrestling with that existential question at the highest levels. Fro

2026 Latest Top-rated AI Illustration Tools: Our curated list features the best powerfully designed tools for creating stunning editorial scenes and eye-catching cover art quickly. Each option has gone through rigorous real-world tests, offering a free vs paid comparison to help you find the perfect match for your workflow. Try these must-try solutions today to unlock your AI edge and boost your creative productivity. Explore now at XIX.AI.
10 tools
xix.ai

2026 Latest Top-Rated Best AI Tutors for Exam Prep are here on XIX.AI! Our curated list features powerful game-changing tools that offer free vs paid comparison, real-world tests, and weekly updated rankings. They help boost your writing efficiency, simplify complex topic learning, and unlock your academic potential. Explore now to Discover your perfect exam prep tool and Start creating today to Unlock your AI edge!
10 tools
xix.ai

2026 Latest Best Top-Rated AI Budget Planning Tools for Personal Money Management are here on XIX.AI! This curated collection features powerful, game-changing solutions that help you conduct real-world tests, understand spending habits, and create personalized plans to boost productivity. Enjoy a free vs paid comparison along with detailed rankings. Must-try tools designed to simplify money management and unlock your AI edge. Explore now!
11 tools
xix.ai

2026 Latest Best Top-Rated AI Sleep Tracking Assistants curated for ultimate recovery. This fully updated weekly guide features powerful tools that deliver real-world tests, free vs paid comparison, and detailed rankings to help you find the must-try solution that boosts sleep quality and supports better bedtime habits. Explore now at XIX.AI to Unlock your AI edge.
10 tools
xix.ai

2026 Latest Best Top-Rated AI SQL Copilots for Product and Revenue Analytics! XIX.AI has curated a powerful, game-changing collection of must-try tools that undergo real-world tests through weekly updated rankings. These tools help users boost productivity significantly by accelerating data analysis, streamlining complex queries, and generating accurate insights to drive smarter business decisions. Explore now to Discover your perfect tool for unlocking your AI edge!
14 tools
xix.ai

2026 Latest Best Top-Rated AI Homework Helpers That Teach Core Concepts Not Just Answers Powerful Tools for Students Must-Try Curated List Weekly Updated Free vs Paid Comparison Real-World Tests Accurate Rankings to Help You Unlock Your Full Learning Potential Explore now to Discover your perfect tool for smarter studying.
10 tools
xix.ai












